Saving money sounds simple until real life gets involved. Rent or a mortgage has to be paid, groceries keep getting more expensive, the car needs gas and maintenance, and another bill always seems to be waiting in your inbox. The good news is that saving more money does not necessarily mean giving up everything you enjoy. The top 10 money-saving tips in this guide focus on practical changes that fit an ordinary American lifestyle without making you feel like you are living on nothing but rice and beans.
Table of Contents
According to the U.S. Bureau of Labor Statistics, the average American consumer unit spent $78,535 in 2024, or about $6,545 per month. Housing and transportation alone represented more than half of average household spending, making those two categories especially important when looking for meaningful savings. That is why the best money-saving strategy is not always about cutting a $5 coffee. Sometimes the biggest opportunity is hiding inside a car payment, insurance bill, grocery habit, subscription, or housing decision.
The following top 10 brilliant money-saving tips are designed to help you find those opportunities. You do not have to use all ten immediately. Start with one or two that match your situation, make them automatic, and then move to the next one. Think of your finances like a leaky bucket: you can keep pouring more money into it, but fixing the leaks is often the smarter first move.
Why Saving Money Matters More Than Ever
Money-saving habits matter because financial pressure can grow quietly. A person may earn a reasonable salary and still feel broke because spending rises along with income. A bigger paycheck can disappear surprisingly quickly when a nicer apartment, a newer vehicle, more restaurant meals, additional subscriptions, and larger shopping trips follow it. The top 10 brilliant money-saving tips are useful because they shift the focus from simply earning more to keeping more of what you already earn.
Saving also gives you something more valuable than a bigger bank balance: flexibility. If your car suddenly needs a $1,200 repair, an emergency fund can prevent that expense from immediately becoming credit-card debt. If your employer reduces your hours, savings can give you breathing room while you look for another opportunity. The Consumer Financial Protection Bureau recommends establishing dedicated emergency savings for unexpected expenses such as car repairs, medical bills, home repairs, or lost income.
Where American Households Spend the Most
The easiest way to understand where to save is to understand where your money is going. Housing was the largest average spending category for American consumer units in 2024, at about $26,266 annually, while transportation averaged $13,318. Food was another major expense, averaging $10,169 annually in 2024. These numbers do not mean every household should spend the same amount, but they show why focusing only on tiny purchases can miss the bigger picture.
Imagine two people trying to save $300 a month. One spends an hour searching for a coupon that saves $8. The other reviews an expensive insurance policy, reduces restaurant spending, renegotiates a recurring bill, and discovers $300 of monthly savings. Both approaches have value, but the second person is attacking the bigger leaks. That is the philosophy behind these top 10 brilliant money-saving tips: look for repeatable savings that can continue month after month instead of relying on occasional bargains.
1. Build a Realistic Monthly Budget
The first of the top 10 brilliant money-saving tips is also one of the most important: create a budget that reflects your real life. A budget is not about restricting yourself; it is about giving your money a clear purpose. It is simply a plan for deciding where your money should go before your money disappears. Start by looking at your take-home pay and then list your regular expenses, including housing, utilities, transportation, insurance, groceries, debt payments, subscriptions, entertainment, and savings.
Many people fail with budgets because they create an unrealistic version of themselves. They assume they will never order takeout, never buy anything online, and never go out with friends. That plan may survive for two weeks, but it usually collapses because it does not account for normal human behavior. A better budget includes room for enjoyment while putting limits around it.
The CFPB recommends looking at cash flow—the timing of money coming in and going out—to build a working budget that matches your circumstances. If you get paid every two weeks, for example, organize your bills and savings around those paydays rather than simply looking at one monthly number. The goal is not to build a perfect spreadsheet; it is to create a simple budget that works for your everyday life. The goal is to make your spending intentional.
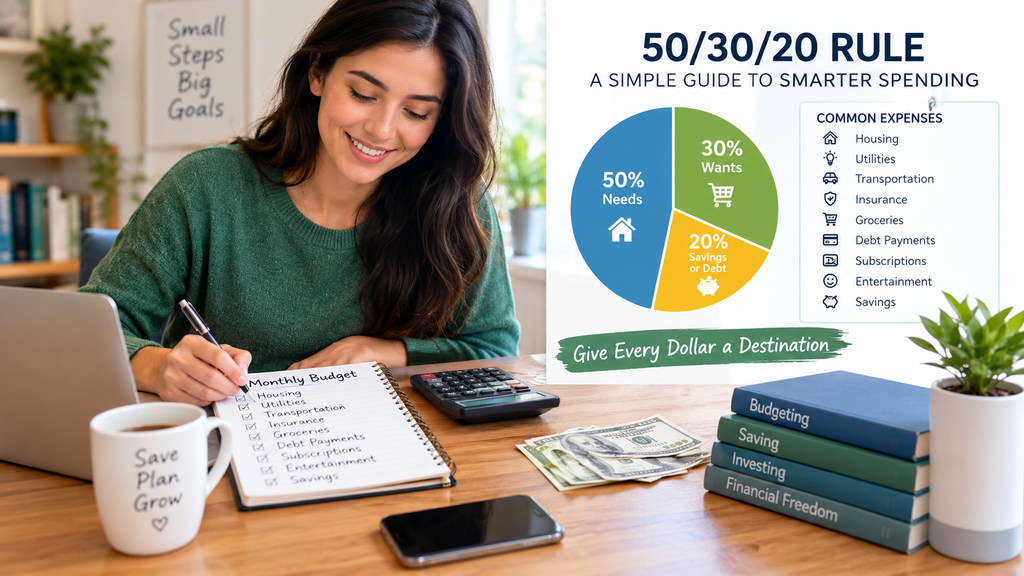
Use the 50/30/20 Rule as a Starting Point.
The popular 50/30/20 framework can provide a simple starting point: roughly 50% of after-tax income for needs, 30% for wants, and 20% for savings or debt repayment.
However, think of it as a flexible guideline rather than a strict rule. Someone living in a high-cost city may spend far more than 50% on housing, while someone with aggressive debt payments may temporarily devote more than 20% to debt reduction.
For example, suppose you bring home $5,000 a month. Instead of wondering where the money went at the end of the month, you could assign approximately $2,500 to essential costs, $1,500 to flexible spending, and $1,000 to savings or debt goals. Your actual numbers may be completely different. What matters is that you give every dollar a destination.
2. Cut the Expenses You Barely Notice
One of the most underrated top 10 brilliant money-saving tips is to attack recurring expenses that happen automatically. A $12 streaming subscription may not look important, but five or six forgotten subscriptions can quietly become $60 or $100 every month. Add premium app memberships, cloud storage, gym fees, meal subscriptions, delivery memberships, and other recurring charges, and the total can become surprisingly large.
Take one month and review your bank and credit-card statements line by line. Do not only look for large purchases. Look for charges that repeat. Ask yourself whether you still use each service enough to justify the cost. If you have not opened an app in three months, paying for it every month is basically renting a room you never enter.
Audit Subscriptions and Recurring Bills
Recurring bills deserve special attention because one decision can produce savings for months or years. Check your cellphone plan, internet package, insurance premiums, streaming services, software subscriptions, gym membership, and other regular charges. Sometimes you can negotiate a lower rate, switch plans, remove unnecessary features, or move to a competing provider.
Suppose you eliminate $75 of unnecessary recurring expenses each month. That is $900 a year before considering what could happen if that money were saved or invested. The power comes from repetition. A one-time $75 saving feels small, but $75 saved every month becomes a meaningful annual amount. This is exactly why recurring expenses belong high on any list of the top 10 brilliant money-saving tips.
3. Make Grocery Shopping More Strategic
Food is one of those expenses that can feel unavoidable, but there is a large difference between paying for food and paying for convenience. In 2024, average consumer-unit spending on food was $10,169, including $6,224 on food at home. That makes grocery planning one of the most practical areas for American households to examine.
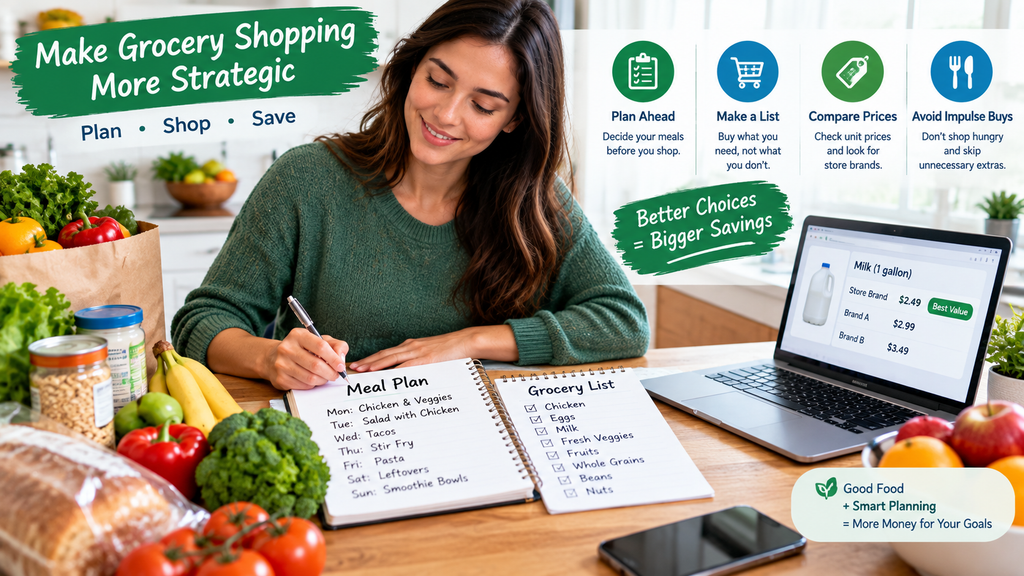
Start by planning several meals before going to the store. Check what you already have in the refrigerator, freezer, and pantry. Then create a shopping list based on meals you actually intend to prepare. Without a plan, it is easy to walk into a supermarket hungry and walk out with snacks, duplicate ingredients, and expensive convenience foods.
Plan Meals Before You Shop
Meal planning does not need to mean eating the same chicken and rice every day. You can create flexible meals around ingredients that overlap. For example, roasted chicken can become dinner one night, a salad topping the next day, and a sandwich filling later in the week. That approach reduces waste while giving you variety.
Compare unit prices instead of automatically choosing the package with the lowest sticker price. Store brands can also be useful when the quality is comparable. And do not confuse a sale with a saving: buying something you would not otherwise purchase is not necessarily a bargain. Among the top 10 brilliant money-saving tips, this one is powerful because it combines planning, lower waste, and smarter purchasing rather than simply telling you to eat less.
4. Reduce Your Transportation Costs
Transportation deserves serious attention because it is one of the largest household expenses in America. BLS data show that average transportation spending was $13,318 in 2024. For many households, the real cost of a vehicle includes much more than the monthly payment. There is fuel, insurance, maintenance, registration, repairs, parking, depreciation, and sometimes financing interest.
If you are buying a car, compare the total cost of ownership rather than focusing only on the monthly payment. A dealer can make a $600 monthly payment sound manageable by extending the loan term, but that does not necessarily make the vehicle affordable. A less expensive car can potentially free hundreds of dollars every month for other goals.
Rethink Car Ownership and Daily Driving
If you already own a vehicle, look for ways to reduce how often and how far you drive. Combining errands into one trip can reduce fuel consumption and save time. If practical, public transportation, biking, walking, carpooling, or working from home part of the week can also reduce transportation costs.
Insurance is another area worth reviewing periodically. Your coverage needs matter, so do not reduce important protection blindly, but compare quotes and check whether your circumstances have changed. Transportation is a perfect example of why the top 10 brilliant money-saving tips are not about tiny sacrifices. A change in a major expense can have a much larger impact than dozens of small coupon-based savings.
5. Automate Your Savings
The fifth of the top 10 brilliant money-saving tips is simple: make saving automatic. If you wait until the end of the month to see what is left, you may discover that nothing is left. Automatic saving reverses that process by moving money toward your goal before discretionary spending has a chance to absorb it.
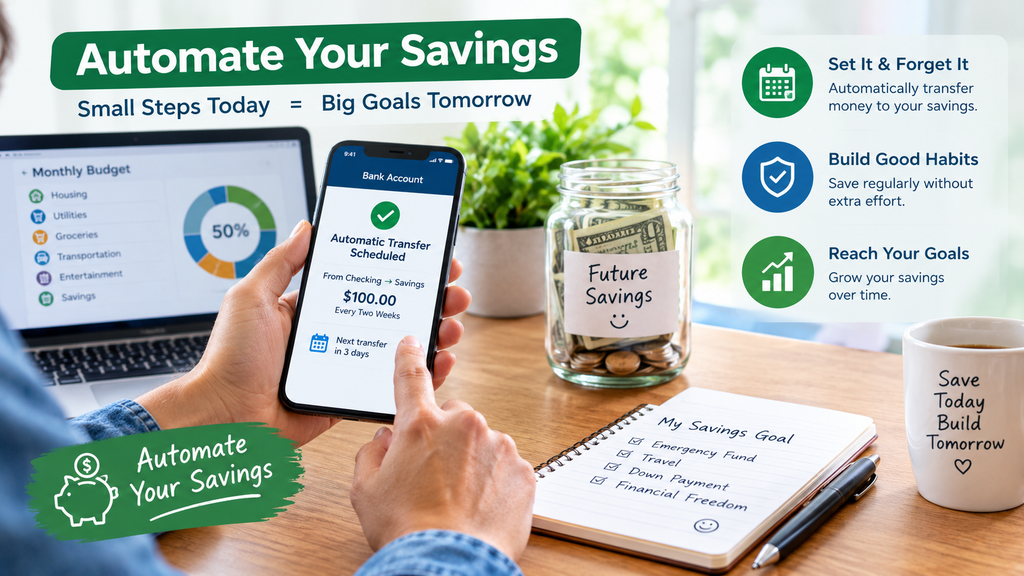
You can arrange an automatic transfer from checking to savings shortly after payday. Some employers also allow employees to divide direct deposits between accounts. The CFPB specifically identifies automatic transfers as an effective way to make saving consistent.
Turn Saving Into a Payday Habit
Start with an amount that will not force you to constantly transfer money back. If $500 per paycheck is unrealistic, perhaps $50 or $100 is a better starting point. The goal is to build the habit first. Once your budget becomes comfortable with the transfer, you can increase it.
Imagine automatically moving $100 from every biweekly paycheck into savings. That would be roughly $2,600 over a year before interest, assuming 26 paychecks. You might barely notice the individual transfers, but the accumulated balance becomes very real. This is one reason automation belongs among the top 10 brilliant money-saving tips: it reduces the need for willpower.
6. Build an Emergency Fund
An emergency fund is your financial shock absorber. Without one, a broken furnace, unexpected medical expense, major car repair, or temporary income loss can push an otherwise healthy budget into debt. The CFPB describes emergency savings as money specifically reserved for unplanned expenses and emphasizes that even small amounts can provide some financial security.
Do not become discouraged if you cannot immediately save several months of expenses. Your first goal might be $500, then $1,000, followed by a larger reserve based on your household’s circumstances. The right amount depends on factors such as income stability, essential expenses, dependents, insurance coverage, and access to other resources.
Start Small and Increase It Gradually
Consider creating a separate savings account for emergencies so the money is not mixed with everyday spending. You want the account accessible when a genuine emergency happens, but not so convenient that you constantly use it for shopping or entertainment.
For example, if you save $25 every week, you will accumulate $1,300 over a year before interest. Increase that to $50 and the annual contribution becomes $2,600. You can also direct part of a tax refund, bonus, or other unexpected income toward the fund. Building a financial cushion is one of the most valuable top 10 brilliant money-saving tips because savings can prevent an unexpected expense from becoming expensive debt.
7. Use Credit Cards More Carefully
Credit cards can be useful financial tools, but they can also make spending feel less painful because the money leaves your account later. One of the smartest top 10 brilliant money-saving tips is to separate convenience from affordability. If you cannot comfortably afford an item without the credit card, the card does not make the purchase affordable.
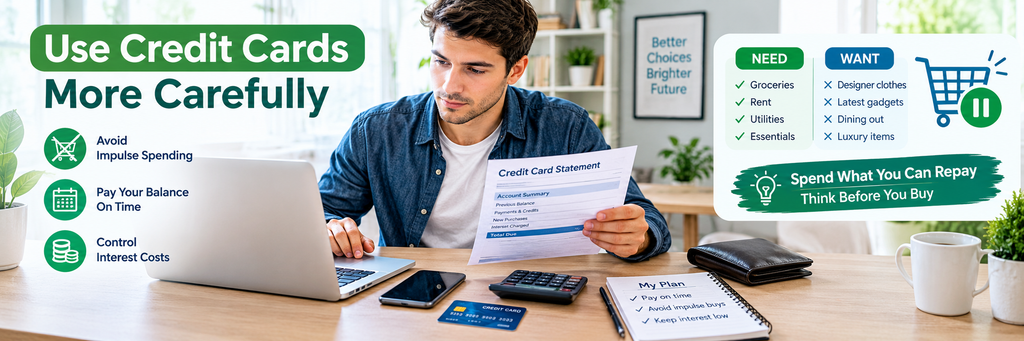
Try treating your credit card like a debit card: spend only what you can pay off. If you already carry a balance at a high interest rate, focus on understanding the interest cost and creating a realistic repayment strategy. Even small reductions in unnecessary purchases can become meaningful when they also reduce future interest.
Avoid Interest and Impulse Spending
Remove saved payment information from shopping websites if it encourages impulse purchases. You can also create a rule that nonessential purchases above a certain amount must wait until the next day. That short pause gives you time to decide whether the item is something you genuinely need or simply something that caught your attention.
Credit-card rewards should never be the reason to spend more. A 2% reward does not turn a $500 unnecessary purchase into a good financial decision. The strongest strategy is to control the purchase first and consider rewards second.
8. Lower Your Energy and Household Bills
Your household bills may feel fixed, but many have flexible components. Heating, cooling, lighting, water usage, appliances, and home maintenance can all affect your monthly costs. You do not need to turn your house into a science experiment. Start with practical changes that fit your home and climate.
Check for drafts around doors and windows, use programmable or smart thermostats appropriately, replace inefficient lighting, and avoid running appliances unnecessarily. If you own your home, larger efficiency improvements may also make sense when the upfront cost is reasonable, and the expected savings justify it.
Make Your Home More Energy Efficient
A simple example is thermostat management. If your home uses significant heating or cooling, even a modest adjustment when you are sleeping or away can reduce energy use. The exact savings will depend on your home, climate, utility rates, equipment, and habits, so think of efficiency improvements as a long-term strategy rather than a guaranteed dollar amount.
Also pay attention to maintenance. A poorly maintained appliance or HVAC system can cost more to operate and may fail earlier. The goal is not to make your home uncomfortable. It is to stop paying for energy and services that do not improve your quality of life. That makes household efficiency a practical addition to the top 10 brilliant money-saving tips.
9. Shop Smarter and Delay Big Purchases
Impulse spending is often less about the item itself and more about timing. Online stores are designed to make purchasing incredibly easy. You see something, click a button, and the decision is over before you have had time to ask whether you actually need it.
One of the best top 10 brilliant money-saving tips is to create a waiting period for nonessential purchases. For smaller purchases, try 24 hours. For expensive purchases, consider waiting several days or even a few weeks. If you still want the item after the waiting period and it fits your budget, you can make a more deliberate decision.
Use the 24-Hour Rule Before Buying.
Suppose you see a $150 gadget online. Instead of buying it immediately, add it to a list and wait until tomorrow. During that time, ask three questions: Do I need it? Do I already own something that performs the same function? And would I rather have the $150 in savings?
This method works because it separates emotion from action. You may discover that many purchases lose their appeal once the excitement disappears. For items you genuinely need, waiting also gives you time to compare prices, search for discounts, read reviews, and determine whether buying used or refurbished makes sense.
10. Give Every Extra Dollar a Purpose
The final tip in the top 10 brilliant money-saving tips is to stop treating unexpected money as automatically spendable. Raises, bonuses, tax refunds, cash gifts, overtime income, and money from selling unused items can create opportunities to accelerate your financial goals.
You do not have to save every extra dollar. Permitting yourself to enjoy some of it can make your overall plan easier to maintain. The key is to decide in advance how you will divide unexpected money. For example, you might save 50%, use 30% for a financial priority, and spend 20% on something enjoyable.
Redirect Windfalls and Raises
Imagine receiving a $4,000 work bonus. Instead of allowing the entire amount to disappear into shopping, travel, and restaurant spending, you could use part of it to build an emergency fund, pay down expensive debt, invest for a long-term goal, and still keep some money for yourself.
The same idea applies to raises. If your take-home pay increases by $300 per month, consider automatically directing a portion of that increase toward savings before your lifestyle expands. This is sometimes called lifestyle inflation control. You still enjoy a better income, but you prevent every increase in earnings from becoming an increase in spending.
The most powerful top 10 brilliant money-saving tips are not necessarily the ones that make you feel deprived. They are the ones that help you turn extra income into lasting financial progress.
Conclusion
The top 10 brilliant money-saving tips are ultimately about making better decisions with the money you already have. Create a realistic budget, eliminate recurring expenses you do not need, plan your groceries, reduce transportation costs, automate savings, build an emergency fund, use credit responsibly, control household energy costs, delay impulse purchases, and give unexpected money a specific purpose.
You do not need to transform your finances overnight. In fact, trying to change everything at once can make the process harder. Choose one area where you can realistically save money this week. Then take the amount you save and redirect it toward something meaningful, such as an emergency fund, debt repayment, retirement, or another financial goal.
Remember that small changes can become large results when they repeat. Saving $50 once is useful. Saving $50 every week is a habit. Saving that money for years while avoiding unnecessary debt can change your financial trajectory.
The real power of the top 10 brilliant money-saving tips is consistency. You are not trying to win a one-day savings challenge. You are building a financial system that makes it easier to keep more of your income, handle surprises, and make progress toward the life you actually want.
Frequently Asked Questions:
1. What is the easiest money-saving tip to start with?
For many people, the easiest starting point is reviewing recurring expenses. Check your bank and credit card statements for subscriptions, memberships, unused services, and recurring charges that you no longer value. Canceling even a few unnecessary expenses can create immediate monthly savings without changing your essential lifestyle. After that, automating the amount you save can help turn those savings into a lasting habit.
2. How much money should I save each month?
There is no single amount that works for every American household. Your ideal savings amount depends on your income, housing costs, debt, family responsibilities, and financial goals. If money is tight, starting with $10, $25, or $50 per paycheck is still worthwhile because consistency matters. As your income rises or expenses fall, increase the amount whenever your budget allows.
3. Should I save or pay off debt first?
It depends on the type and interest rate of the debt, your emergency savings, and your overall financial situation. Building at least a small emergency cushion can help prevent every unexpected expense from going onto a credit card. After that, high-interest debt often deserves significant attention because interest can work against your financial progress. A balanced approach can allow you to save something while aggressively reducing expensive debt.
4. How can I save money when my income is low?
Start with the expenses you can actually control rather than trying to copy someone else’s budget. Review subscriptions, food spending, transportation, insurance, utilities, and discretionary purchases. Track your cash flow so you know when money arrives and when bills are due. The CFPB notes that even small emergency savings can provide some financial security, so do not assume that saving is pointless unless you can put away a large amount.
5. What are the top 10 brilliant money-saving tips for beginners?
The top 10 brilliant money-saving tips include creating a monthly budget, tracking spending, automating savings, reducing grocery costs, canceling unused subscriptions, lowering utility bills, comparing insurance, using credit cards responsibly, shopping strategically, reducing transportation costs, and building an emergency fund. Beginners should start with the strategies that require the least effort and produce recurring savings. Automating savings and eliminating unnecessary recurring expenses are often good starting points.
6. How can I save money when my income is limited?
When income is limited, start small rather than waiting until you can save a large amount. Track your expenses, identify recurring charges you can eliminate, reduce food waste, compare insurance and service costs, and automate even a small savings transfer. The CFPB notes that even small amounts can provide some financial security and recommends developing consistent savings habits.
7. How much money should I save each month?
There is no single monthly amount that works for every American household. Your savings target depends on income, essential expenses, debt, household responsibilities, job stability, and financial goals. If you are starting from zero, choose an amount that you can consistently maintain rather than setting an unrealistic target. Once the habit is established, gradually increase the amount when your income rises or expenses fall.
8. What is the easiest of the top 10 brilliant money-saving tips to start today?
Automating a small transfer into a dedicated savings account is one of the easiest strategies because it reduces the need for repeated decisions. You can also review your recurring subscriptions and cancel services you no longer use. Both strategies can create recurring savings without requiring a major lifestyle change. The CFPB has recommended automatic transfers as one way to establish a savings habit.
9. How quickly can these money-saving tips improve my finances?
You can potentially see an immediate improvement in your monthly cash flow once you eliminate unnecessary expenses. However, meaningful financial progress usually comes from repeating those savings over many months and years. For example, saving $250 per month creates $3,000 over one year before any interest or investment growth. The goal of the top 10 brilliant money-saving tips is therefore not a one-time financial win but a sustainable system that keeps more of your income available for your goals.
10. How quickly can these money-saving tips make a difference?
Some changes can have an immediate effect, while others take months or years. Canceling an unused subscription can reduce your next month’s expenses, while building an emergency fund takes longer. The important factor is repetition. If you consistently redirect savings toward your financial goals, even relatively small monthly improvements can accumulate into a meaningful amount over time.
3 thoughts on “Top 10 Brilliant Money-Saving Tips”